
Rain Instant Pay
- Rating
- 4.7
- Downloads
- 500.00K
- Content Rating
- Everyone
Rain Instant Pay - Screenshots
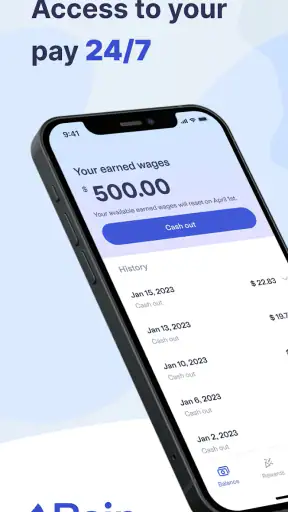
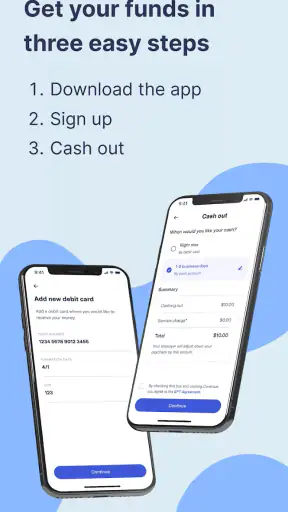
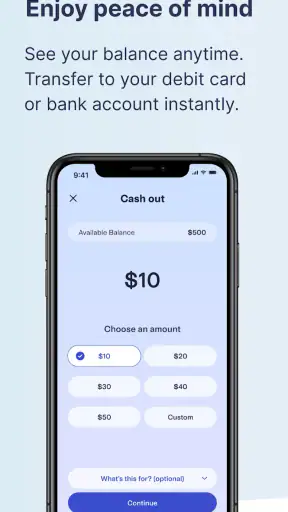
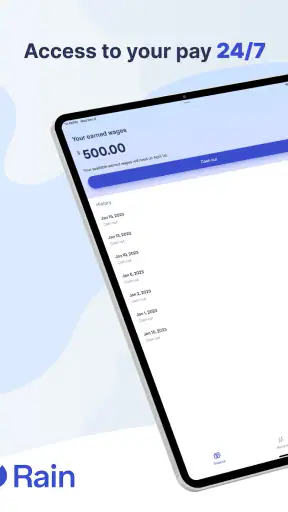
Pros
- Fast access to earned wages without waiting for the usual payday.
- Simple interface makes checking available earnings quick and convenient.
- Can help cover unexpected expenses between regular paychecks.
- Secure sign-in options help protect personal and payment information.
- Useful for workers whose employers support on-demand wage access.
Cons
- Availability depends on employer participation and payroll system compatibility.
- Instant transfers may include fees
- depending on the selected delivery method.
- Access limits can reduce how much of your earned pay is available early.
- A delayed payday may make budgeting harder if used too frequently.
- Support response times may vary when resolving payment or account issues.
Rain Instant Pay - Description
- App Name
- Rain Instant Pay
- Package Name
- us.rain.app
- Developer
- Rain Technologies Inc
- Category
- Business
- Last Updated
- Feb 1, 2020
- Version
- 2.10.1
When an unexpected bill arrives before payday, the usual choices are uncomfortable: delay the payment, ask someone for help, or rely on a credit option that can make the next pay cycle harder. Rain Instant Pay is designed for a different situation. It connects eligible employer benefits with access to earned pay, giving me a way to handle a short-term cash gap without treating every emergency like a long-term borrowing problem.
After spending time with the app, I see it as a focused business and employee-benefits tool, not a general budgeting platform. Its value depends heavily on whether my employer participates and whether the available benefit fits the way I am paid. When those conditions line up, the experience can be practical and reassuring. When they do not, the app has little to offer, so checking eligibility early is the most important first step.
Where Rain fits before I need it
The best time to think about Rain is before a financial surprise happens. If I wait until a utility payment is due or a car problem needs immediate attention, I am already making decisions under pressure. A more sustainable routine is to install the app, check whether my employer is supported, understand how access works, and then leave it ready for a genuine need rather than treating early pay as extra spending money.
This distinction matters. Instant access to earnings can solve a timing problem, but it does not increase my overall income. I still need to account for the amount that will be available in the normal paycheck. In my experience, the app makes the most sense as a controlled bridge between an expense and payday, not as a replacement for an emergency fund or a monthly spending plan.
Rain Technologies Inc developed the app for this employer-connected use case. That means the experience is different from a typical personal finance app that I can open and use independently. My employer relationship is part of the setup, so the first useful question is not whether the interface looks appealing; it is whether my workplace offers the relevant benefit and whether my employment information matches what the app expects.
The app is free to install and carries an Everyone age rating, which makes it approachable for a broad audience. It was released on February 1, 2020, and the current version is 2.10.1. Those details are less important than the practical test: can I verify access quickly, understand the available amount, and use it without losing track of my normal pay cycle?
Starting with a clear financial purpose
I would not recommend opening Rain simply because the idea of earlier pay sounds convenient. Before using it, I would name the expense and decide whether accessing money early genuinely improves the situation. A necessary prescription, a late bill that would trigger a serious consequence, or a transport repair needed to get to work is a different case from impulse shopping or a weekend upgrade.
That small pause creates a useful boundary. If the expense is important and temporary, the service may reduce stress. If I am repeatedly using early pay to cover ordinary living costs, the problem is probably larger than the timing of one paycheck. In that situation, a spending review, a conversation with payroll, or a conventional savings plan may be more helpful than another withdrawal.
Another sensible preparation step is to keep the app’s role separate from other money tools. I would use a banking app to see the full account balance, a calendar for due dates, and a budget to decide what I can afford. Rain can sit between those tools as an access point for eligible earnings, but it should not become the only place where I monitor my financial position.
Capturing the information that actually matters
Rain is not a note-taking app, so “capture” here means capturing the right context before I act. I would record the bill amount, its due date, the amount I expect in my next regular paycheck, and the amount I am considering accessing. This can be a simple note elsewhere, but it prevents a common mistake: focusing on the amount available now while forgetting the smaller paycheck that follows.
A useful personal rule is to treat the accessed amount as already spent. Once I use it for the intended bill, I would not count it again when planning groceries, transport, or other essentials. This mental separation is more valuable than repeatedly checking the app. It turns Rain from a source of tempting availability into a deliberate part of a cash-flow plan.
I would also keep a short record of each use: why I accessed the money, how much I took, and whether the next pay cycle felt manageable. That record can reveal whether the app is solving occasional timing issues or masking a recurring shortfall. The insight is easy to miss because an individual transaction may feel harmless, while a pattern becomes visible only after several pay cycles.
For someone paid on a regular schedule, this approach is fairly straightforward. For someone whose hours change often, the available amount may be harder to plan around. I would be especially cautious if shifts, tips, overtime, or payroll corrections regularly change expected earnings. In that case, I would verify the amount shown in the app against my own recent pay information before committing it to a bill.
Building a repeatable routine instead of reacting
A repeatable Rain routine can be very simple. At the start of each pay period, I would review upcoming essential expenses, identify any genuine gap, and decide whether using the benefit is necessary. If I use it, I would immediately update my personal budget and treat the next paycheck as reduced by that amount. At the next payday, I would check whether the plan worked as expected.
This routine has three advantages. It limits emotional decisions, makes the effect on the next paycheck visible, and gives me a stopping point. Without a stopping point, instant access can feel like an open-ended solution to every small inconvenience. With one, it remains a targeted tool for timing problems.
I would also avoid making an access decision while distracted at work or in a hurry. A few minutes spent checking the destination account, the bill, and the next pay cycle can prevent an avoidable mistake. The app may make the transaction feel quick, but quick access should not mean careless planning.
Rain’s strong point is this immediacy. Compared with asking a friend, waiting for a bank transfer, or applying for a traditional credit product, an employer-linked earned-pay option can be more direct when I am eligible. It also keeps the decision connected to money I have already earned rather than asking me to borrow against a distant promise of repayment.
That comparison has limits. A bank account remains better for seeing all income and expenses in one place. A savings account is better for building resilience over time. A credit card may be more suitable for a purchase that must be paid over multiple months, provided I understand the cost and repayment terms. Rain is best when the problem is short-term timing and the amount can be absorbed by the upcoming pay cycle.
What can interrupt the experience
The first possible friction is eligibility. Because Rain works through employer benefits, I cannot assume that downloading it guarantees access. Employment details, workplace participation, and payroll information all matter to the experience. If the app cannot connect me to the relevant benefit, that is not something I can solve by repeatedly reinstalling it; I would need to check with my employer or payroll contact.
The second issue is expectation management. The store summary presents the app as a way to unlock employer benefits, while the short description focuses on instant pay. I would read that as a sign to explore the available benefit carefully rather than assuming every user receives identical access. The exact usefulness can depend on how my workplace has arranged the benefit and how my earnings are recorded.
A third failure point is relying on the displayed availability without checking the real-world deadline. Even if money can be accessed quickly, a bill may require processing time, a transfer may not arrive when I expect, or the receiving organization may have its own cutoff. I would never wait until the final minute for rent, a medical payment, or a work-critical expense simply because the app is built around speed.
There is also a behavioral risk. The convenience can make a recurring deficit feel temporary. If I need Rain every pay period for groceries or housing, I would stop and investigate the underlying budget. The app may be functioning correctly while my financial plan is not. That is an important limitation because no instant-pay service can turn insufficient monthly income into sustainable cash flow.
Privacy and account security deserve ordinary caution as well. I would use a strong device lock, avoid signing in on shared phones, and review every confirmation before approving access. I would also keep notifications useful rather than allowing them to become a constant prompt to withdraw money. These are not special Rain features; they are habits that help prevent a convenience tool from becoming a source of impulsive decisions.
How the app feels in everyday use
The most realistic scenario is a midweek car repair that I need in order to keep commuting to work. Before Rain, I might compare a bank balance, ask whether the mechanic accepts delayed payment, or consider a costly borrowing option. With an eligible employer benefit, I could check the app, compare the available amount with the repair bill, and access only what I need. I would then update my budget so the next paycheck is planned around the earlier access.
The important part is not merely obtaining money faster. It is the sequence around the transaction: confirm the need, take the minimum useful amount, understand the effect on payday, and avoid using the remaining availability for unrelated purchases. That workflow is where I think Rain can be genuinely helpful.
Another use case is a bill whose due date falls just before payday. Here, I would compare the consequences of paying early with the consequences of waiting. If a short delay has no penalty, waiting may be the better choice. If missing the date creates a serious problem and I can comfortably absorb the reduction in my next paycheck, Rain may be a reasonable bridge.
I would be less enthusiastic about using it for a purchase that I simply want today. The psychological difference between “I need to prevent a problem” and “I want to buy this before payday” is easy to blur when access is immediate. Keeping that distinction visible is one of the most useful safeguards I can recommend.
Who will benefit most from adopting it
Rain is a strong candidate for employees whose workplace supports it, whose pay is already earned but arrives on a fixed schedule, and who occasionally face expenses that cannot wait. It may also suit people who dislike conventional borrowing for small, short-lived gaps and who are disciplined enough to adjust their next-paycheck budget immediately.
It is less suitable for someone looking for a full budgeting dashboard, automatic long-term savings, debt management, or investment guidance. Those needs belong to other financial tools. It is also a poor fit for anyone whose income is consistently lower than essential expenses. Early access can change timing, but it cannot repair that structural mismatch.
People with irregular hours should approach it with extra care. I would not plan a fixed bill around the highest recent earnings if my schedule changes from week to week. I would use conservative estimates, check payroll details, and keep a separate buffer whenever possible. The app is easier to use responsibly when my expected pay is predictable.
The service has attracted substantial attention, with an average rating of 4.7 from around 34 thousand ratings and more than 500 thousand installs. I take that as evidence that many people find the basic idea useful, but popularity does not remove the need to understand my own employer arrangement and spending pattern. A highly rated access tool can still be the wrong choice for a person who needs budgeting support rather than earlier pay.
My final assessment after fitting it into a routine
Rain Instant Pay works best when I treat it as a controlled part of a broader productivity and money routine. It can reduce the time spent scrambling for a small, urgent amount, and its employer-benefit model gives it a different role from a normal banking or credit app. The strongest experience comes from preparing before the emergency, using only the necessary amount, and planning for the next paycheck immediately.
My main reservation is not the concept itself but the temptation to confuse convenience with affordability. If I use the app occasionally for a genuine timing problem, it can be a useful safety valve. If I depend on it repeatedly for ordinary expenses, I would choose a deeper financial review instead. The app should make a workable plan easier to execute, not make an unworkable plan look acceptable.
For eligible employees who want a direct way to access earned pay, the free app is worth exploring. I would install it, confirm how my employer benefit works, and test my personal routine with a small, clearly defined need rather than making it part of every pay cycle. That approach preserves its practical advantage while keeping my larger financial system stable.
Rain Technologies Inc has kept the product focused on a specific workplace problem, and that focus is its biggest strength. It will not replace a bank, a budget, or an emergency fund. Used with those tools, however, it can be a sensible option when payday timing—not total income—is the obstacle.
FAQ
What is Rain Instant Pay and how does it work?
Rain Instant Pay is a financial service designed to give eligible users faster access to part of their earned wages before the usual payday. After creating an account and connecting the required employment or payroll information, the app may display an available amount that can be transferred to a supported bank account or payment card. Availability, limits, and delivery times can vary depending on employer participation, verification, and account status.
Is Rain Instant Pay safe to use with my personal and financial information?
Rain Instant Pay may require sensitive details such as your identity information, employment data, bank account, or debit card details to verify eligibility and process transfers. Before signing up, review the app’s privacy policy, security information, and permissions carefully. Use a strong password, enable any available security features, and download the application only from an official app store to reduce the risk of installing an imitation.
How quickly will I receive money through Rain Instant Pay?
Transfer speed depends on the delivery method selected, your bank or card provider, verification results, and whether the transaction is processed during business hours. Some users may receive funds quickly, while standard transfers can take longer. The app should show the estimated arrival time and any applicable charge before confirmation, so check those details carefully rather than assuming every transfer is immediate.
Does Rain Instant Pay charge fees for accessing or transferring money?
The cost of using Rain Instant Pay can depend on the type of transaction, the delivery option, and the terms offered through your employer or account. Certain features may be free, while faster delivery or particular transfer methods may involve a fee. Always review the final confirmation screen, including the amount received and any charges, before authorizing an advance or withdrawal.
Who is eligible to use Rain Instant Pay, and what happens if I change jobs?
Eligibility is generally connected to participating employers, payroll verification, location, age, and other account requirements. Not every worker will be able to register or access the same features, even if the app is available for download. If you change jobs, leave a participating employer, or your payroll information changes, access may be reduced or suspended until the new employment details are verified.


